
If you’re enrolled in Original Medicare, you may have questions about the healthcare costs that Medicare doesn’t pay in full. That’s where Medigap, also called Medicare Supplement Insurance, may help.
What is Medigap? Medigap is supplemental insurance sold by private insurance companies that can help pay certain out-of-pocket costs associated with Original Medicare, including some copayments, coinsurance, and deductibles. Medicare
Medigap isn’t a replacement for Medicare. Instead, it works alongside Original Medicare to help reduce certain costs you may otherwise have to pay yourself.
Understanding how Medigap works, what it covers, when you can buy it, and how it differs from Medicare Advantage can help you make a more informed Medicare coverage decision.
What Is Medigap?
Medigap is another name for Medicare Supplement Insurance.
It’s private insurance designed to help pay some of the healthcare costs that remain after Original Medicare pays its share.
Original Medicare includes:
- Medicare Part A — Hospital Insurance
- Medicare Part B — Medical Insurance
When you receive covered healthcare services under Original Medicare, Medicare generally pays its share of the Medicare-approved amount. Depending on the service, you may still have deductibles, coinsurance, or copayments.
A Medigap policy can help pay some of these remaining costs, depending on the plan you choose. Medicare
Generally, you need both Medicare Part A and Part B to purchase a Medigap policy. Medicare
How Does Medigap Work?
Medigap works alongside Original Medicare.
For example, suppose you receive a Medicare-covered medical service.
The process generally works like this:
- You receive a covered healthcare service.
- Original Medicare pays its share of the Medicare-approved amount.
- Your Medigap policy may pay some of the remaining eligible costs according to the policy.
- You pay any costs that aren’t covered by Medicare or your Medigap policy.
The amount Medigap pays depends on the specific plan you have.
That’s why it’s important to understand the benefits associated with each Medigap plan before purchasing a policy. Medicare
What Does Medigap Cover?
Medigap plans are designed to help with certain costs associated with Original Medicare Part A and Part B.
Depending on the plan, Medigap may help pay for:
- Part A coinsurance
- Hospital costs after Medicare benefits are used
- Part B coinsurance or copayments
- Part A deductible
- Part B deductible, depending on the plan and eligibility
- Skilled nursing facility coinsurance
- Certain foreign travel emergency expenses
The benefits vary by Medigap plan. Medicare
Not every Medigap plan provides the same benefits, so comparing plan letters is important.
What Doesn’t Medigap Cover?
Medigap isn’t designed to cover every healthcare expense.
Generally, Medigap policies don’t cover:
- Long-term care
- Routine dental care
- Vision care
- Eyeglasses
- Hearing aids
- Private-duty nursing
- Prescription drugs
If you want Medicare prescription drug coverage, you can generally enroll in a separate Medicare Part D plan when appropriate. Medicare
For dental, vision and hearing coverage, separate coverage options may be available depending on your circumstances.
Learn more about Medicare dental, vision and hearing coverage.
Are Medigap Plans Standardized?
Yes. In most states, Medigap policies are standardized and identified by letters.
Examples include:
- Plan A
- Plan B
- Plan C
- Plan D
- Plan F
- Plan G
- Plan K
- Plan L
- Plan M
- Plan N
The benefits of a particular lettered plan are generally standardized, meaning a Plan G from one insurance company provides the same basic Plan G benefits as a Plan G from another company.
However, the price can differ between insurance companies. Medicare
Massachusetts, Minnesota, and Wisconsin have different Medigap standardization systems. Medicare
What Is Medigap Plan G?
Medigap Plan G is one of the standardized Medigap plans available in most states.
It provides broad coverage for many Medicare cost-sharing expenses, although it does not cover the Medicare Part B deductible for people newly eligible for Medicare under current federal rules.
Plan availability and pricing can vary by state and insurance company.
When comparing Plan G policies, remember that the benefits for the same standardized plan are generally the same, while the premium and pricing structure can differ.
What Is Medigap Plan N?
Medigap Plan N is another standardized Medigap option.
Plan N covers many of the same types of Medicare cost-sharing expenses as other Medigap plans, but you may have certain copayments for some office visits and emergency room visits.
Medicare.gov currently notes that Plan N may require a copayment of up to $20 for some office visits and up to $50 for emergency room visits when you aren’t admitted as an inpatient. Medicare
The trade-off between premiums and cost-sharing is one reason people compare different Medigap plans based on their expected healthcare needs.
How Much Does Medigap Cost?
There isn’t one nationwide Medigap price.
Your Medigap premium can depend on factors such as:
- The plan you choose
- Where you live
- The insurance company
- Your age
- How the insurance company prices its policies
- When you purchase the policy
- Your health circumstances, depending on applicable enrollment and underwriting rules
Medicare.gov notes that Medigap premiums vary by policy and location and may change over time. Medicare
When comparing Medigap policies with the same letter, don’t assume that the most expensive policy provides better standardized benefits. For the same lettered plan, the basic benefits are standardized, while prices can differ between insurers. Medicare
When Is the Best Time to Buy Medigap?
One of the most important things to understand about Medigap is the Medigap Open Enrollment Period.
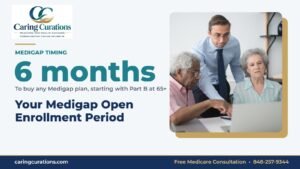
Your federal Medigap Open Enrollment Period generally lasts 6 months. It begins when you’re 65 or older and enrolled in Medicare Part B.
During this period, you generally have important protections when buying a Medigap policy, including the ability to purchase available Medigap policies without medical underwriting based on pre-existing health conditions. Medicare
After this period, you may have fewer options, and a policy may cost more depending on your circumstances and state rules. Medicare
This is different from Medicare’s Annual Enrollment Period. Medigap Open Enrollment is a one-time period and doesn’t repeat every year. Medicare
Can You Have Medigap and Medicare Advantage?
No. You generally can’t have Medigap and Medicare Advantage at the same time.
Medigap supplements Original Medicare.
Medicare Advantage, also called Part C, is an alternative way to receive Medicare Part A and Part B benefits through a Medicare-approved private plan.
If you have Medicare Advantage, you can’t use a Medigap policy to pay your Medicare Advantage copayments, deductibles, or premiums. Medicare
If you’re comparing these options, see our guide to Medicare Advantage plans.
Medigap vs. Medicare Advantage
These two types of coverage are often confused, but they work very differently.
| Feature | Medigap | Medicare Advantage |
|---|---|---|
| Works with Original Medicare | Yes | No |
| Alternative to Original Medicare | No | Yes |
| Sold by private insurers | Yes | Yes |
| Helps pay Original Medicare cost-sharing | Yes | No |
| Prescription drug coverage | Generally no | Most plans include Part D |
| Provider networks | Generally not the same network structure as Medicare Advantage | Plan network rules may apply |
| Separate monthly premium | Usually | Varies by plan |
| Can have both simultaneously? | No | No |
Medicare describes Medigap as supplemental coverage that helps pay your share of Original Medicare costs, while Medicare Advantage is an alternative way to receive Medicare coverage. Medicare
Do You Still Pay the Medicare Part B Premium With Medigap?
Yes.
Having Medigap doesn’t replace your Medicare Part B premium.
You generally pay:
Medicare Part B premium + Medigap premium
Medicare.gov specifically notes that you must continue paying your Part B premium to keep your Medigap coverage. Medicare
This is an important consideration when calculating your overall Medicare healthcare budget.
Does Medigap Include Prescription Drug Coverage?
Generally, no.
Medigap policies sold after 2005 don’t include prescription drug coverage.
If you want Medicare prescription drug coverage while using Original Medicare and Medigap, you can generally consider a separate Medicare Part D plan. Medicare
You can learn more about prescription coverage in our Medicare Part D guide.
Is Medigap Right for You?
There isn’t one Medicare option that works for everyone.
Medigap may be worth considering if you:
- Prefer Original Medicare
- Want supplemental coverage for certain Medicare cost-sharing
- Want the flexibility associated with Original Medicare
- Want to reduce uncertainty around certain out-of-pocket costs
- Are willing to pay a separate Medigap premium
Your healthcare needs, budget, preferred doctors, location, and eligibility can all affect your decision.
Before choosing a policy, compare the benefits, premiums, company pricing, and applicable enrollment rules.
7 Things to Know Before Buying Medigap
Before purchasing a Medigap policy, consider these seven points:
1. You Need Original Medicare
You generally need both Part A and Part B to purchase Medigap.
2. Medigap Doesn’t Replace Medicare
It supplements Original Medicare rather than replacing it.
3. Plans Are Standardized
In most states, lettered Medigap plans have standardized benefits.
4. Prices Can Vary
Different companies can charge different premiums for the same standardized plan.
5. Timing Matters
Your Medigap Open Enrollment Period provides important protections.
6. Medigap Doesn’t Include Most Prescription Coverage
You generally need separate Part D coverage for Medicare prescription drugs.
7. Medigap and Medicare Advantage Are Different
You generally choose between using Medigap with Original Medicare or enrolling in Medicare Advantage. Medicare
What Is Medigap Plan G vs Plan N? Side-by-Side
Plan G and Plan N are the two Medigap plans people new to Medicare compare most often. Here is how they differ in 2026. (Medicare.gov)
| Feature | Plan G | Plan N |
|---|---|---|
| Part A deductible ($1,736) | Covered | Covered |
| Part B deductible ($283) | You pay | You pay |
| Part B coinsurance | Covered | Covered, except copays of up to $20 for some office visits and up to $50 for some ER visits |
| Part B excess charges | Covered | Not covered |
| Skilled nursing coinsurance | Covered | Covered |
| Foreign travel emergency | 80%, up to plan limits | 80%, up to plan limits |
| Monthly premium | Usually higher | Usually lower |
Part B excess charges are extra amounts, up to 15% above the Medicare-approved amount, that some doctors who don’t accept Medicare assignment can bill. Several states, including New York, limit or prohibit them, which can make Plan N more attractive.
What Is Medigap High-Deductible Plan G?
Some insurers offer a high-deductible version of Plan G. It has the same benefits as Plan G, but you pay Medicare-covered costs up to a deductible first. In 2026 the deductible is $2,950. Premiums are usually much lower, so it can suit healthy people who want protection against large bills but rarely see the doctor.
Why Plans C and F Aren’t Available to Everyone
Medigap Plans C and F cover the Part B deductible. Since 2020, they can only be sold to people who were eligible for Medicare before January 1, 2020. If you became eligible later, Plan G offers nearly identical coverage, minus the Part B deductible.
How Medigap Premiums Are Set
Medigap insurers use one of three pricing methods: community-rated (generally the same price for everyone), issue-age-rated (based on your age when you buy) or attained-age-rated (rises as you age). Any of them can also rise with inflation. Two policies with the same letter may cost very different amounts over time, so ask how a company prices its plans before you buy.
Medigap in New York
If you live in New York, you have extra protections. Medigap insurers in New York must accept applications year-round, and premiums can’t be based on your age or health. That means you aren’t limited to a one-time open enrollment window to buy or switch plans. Learn more in our guide to Medicare Supplement Insurance.
Can You Switch Medigap Plans?
Yes. You can apply for a different Medigap plan at any time, but outside your Medigap Open Enrollment Period or a guaranteed issue situation, most insurers can ask health questions and may decline you or charge more. Don’t cancel your current policy until your new one is approved. Some states, such as New York, offer broader rights to switch.
What Is Medigap Not? 4 Common Myths
Knowing what Medigap doesn’t do is just as useful as knowing what it does. Here are four myths we hear often:
- Myth: Medigap replaces Medicare. It doesn’t. You keep Original Medicare and keep paying your Part B premium. Medigap only pays some of the costs Medicare leaves behind.
- Myth: A more expensive Plan G has better benefits. Plan G benefits are the same from every company in most states. A higher price doesn’t buy better coverage, though service and rate history can differ.
- Myth: Medigap covers prescriptions. Policies sold today don’t. You need a separate Part D plan for drug coverage.
- Myth: You can buy Medigap any time with no questions. In most states that’s only true during your Medigap Open Enrollment Period or a guaranteed issue situation. New York is a notable exception.
If you are still asking yourself “what is Medigap going to cost me, and is it worth it?”, a side-by-side quote for the same plan letter from several companies is the best next step.
Frequently Asked Questions About Medigap
What is Medigap?
Medigap is Medicare Supplement Insurance sold by private insurance companies to help pay certain out-of-pocket costs associated with Original Medicare.
Is Medigap the same as Medicare Supplement Insurance?
Yes. Medigap is the common name for Medicare Supplement Insurance.
Can I have Medigap with Medicare Advantage?
No. You generally can’t use Medigap while enrolled in Medicare Advantage. Medicare
Does Medigap cover dental and vision?
Generally, no. Medigap generally doesn’t cover routine dental or vision care, glasses, or hearing aids. Medicare
Does Medigap cover prescriptions?
Generally, no. Medigap policies sold after 2005 don’t include prescription drug coverage. A separate Part D plan may provide prescription coverage. Medicare
When should I buy Medigap?
The federal Medigap Open Enrollment Period generally lasts six months and begins when you’re 65 or older and enrolled in Part B. This period can provide important protections when purchasing a policy. Medicare
What is Medigap Plan G vs Plan N?
Both cover most Medicare cost-sharing. Plan N usually has a lower premium but adds small copays for some office and ER visits and doesn’t cover Part B excess charges.
How much is the high-deductible Plan G deductible in 2026?
It is $2,950 in 2026. After you reach it, the policy pays like a standard Plan G for the rest of the year.
What is Medigap Plan F, and can I still buy it?
Plan F covers all Medicare cost-sharing, including the Part B deductible. You can only buy it if you were eligible for Medicare before January 1, 2020. Otherwise, Plan G is the closest option.
Related guides: Plan G vs Plan N, Does Medicare cover hearing aids? and Medicare Part B.
Final Thoughts
If you are comparing options for yourself or a parent, a short conversation can answer the questions that matter most: what is Medigap likely to cost where you live, which plan letter fits your health needs, and what is Medigap’s role alongside a Part D drug plan. We can walk you through each one and compare quotes from several companies at no cost to you.
So, what is Medigap?
Medigap is supplemental insurance that works with Original Medicare to help pay certain out-of-pocket healthcare costs, such as copayments, coinsurance, and deductibles.
Because Medigap plans are standardized in most states, comparing the benefits of different plan letters and then comparing premiums between insurance companies can help you understand your options.
At Caring Curations Medicare and Health Advisors, we provide personalized guidance to help you understand Medicare coverage options, including Medicare Supplement Insurance, Medicare Advantage, prescription drug coverage, and additional insurance options.
Guidance you trust. Care you can count on.



16 Responses